ESG UQAM · Assistant Professor of Finance

The stock market
is going passive.

I study the consequences.

Pouya Behmaram

Asset PricingPassive InvestingInstitutional InvestorsOptions & Retail InvestorsSustainable Finance
Pouya Behmaram, Assistant Professor of Finance, ESG UQAM

ESG UQAM

Montréal, Canada

Research Agenda

Four questions about what investors actually do

What an investor is called says little about what it does. A fund called active can hold mostly its benchmark. A fund's carbon score can fall without its manager trading toward greener firms. Retail traders reveal in public which stocks they are crowding into. I measure what investors actually do, and trace what it means for prices and portfolios.

01Passive investing

What does index money do to prices?

Index funds hold whatever the index holds, whatever its price. The most indexed stocks have demand about half as elastic as the least indexed, so the same order moves their price further. As index money arrived, prices rose faster than earnings forecasts: a point of indexed ownership is worth about 1.4 percent of a stock's value. Existing shareholders kept the gains; later buyers get lower expected returns.

Indexing and the Elasticity of Stock Demand (with Carter Davis)The Price of Passive Ownership

NextHow active managers compete with a nearly free index fund (with Laurent Barras and David Schumacher), in progress

02Passive investing

What happens when a firm sells new shares to buyers who must buy?

Index funds must buy part of every new share issue by firms they already hold, in amounts and on dates fixed by index rules before the deal is priced. These purchases grew from about 2 percent of the money raised in follow-on offerings in 2002 to nearly 16 percent in 2023. Firms selling into more of this scheduled demand sell their shares at higher prices.

03Sustainable finance

Did the fund get greener, or did its companies?

Since 2019, U.S. fund carbon intensity, emissions per dollar of sales, has fallen by about a third. The decline happened to the funds, not through them. Managers' trading explains less than a tenth; rising sales drove most of it, and higher output prices alone about half.

04Retail investors & options

Do option prices know what Reddit knows?

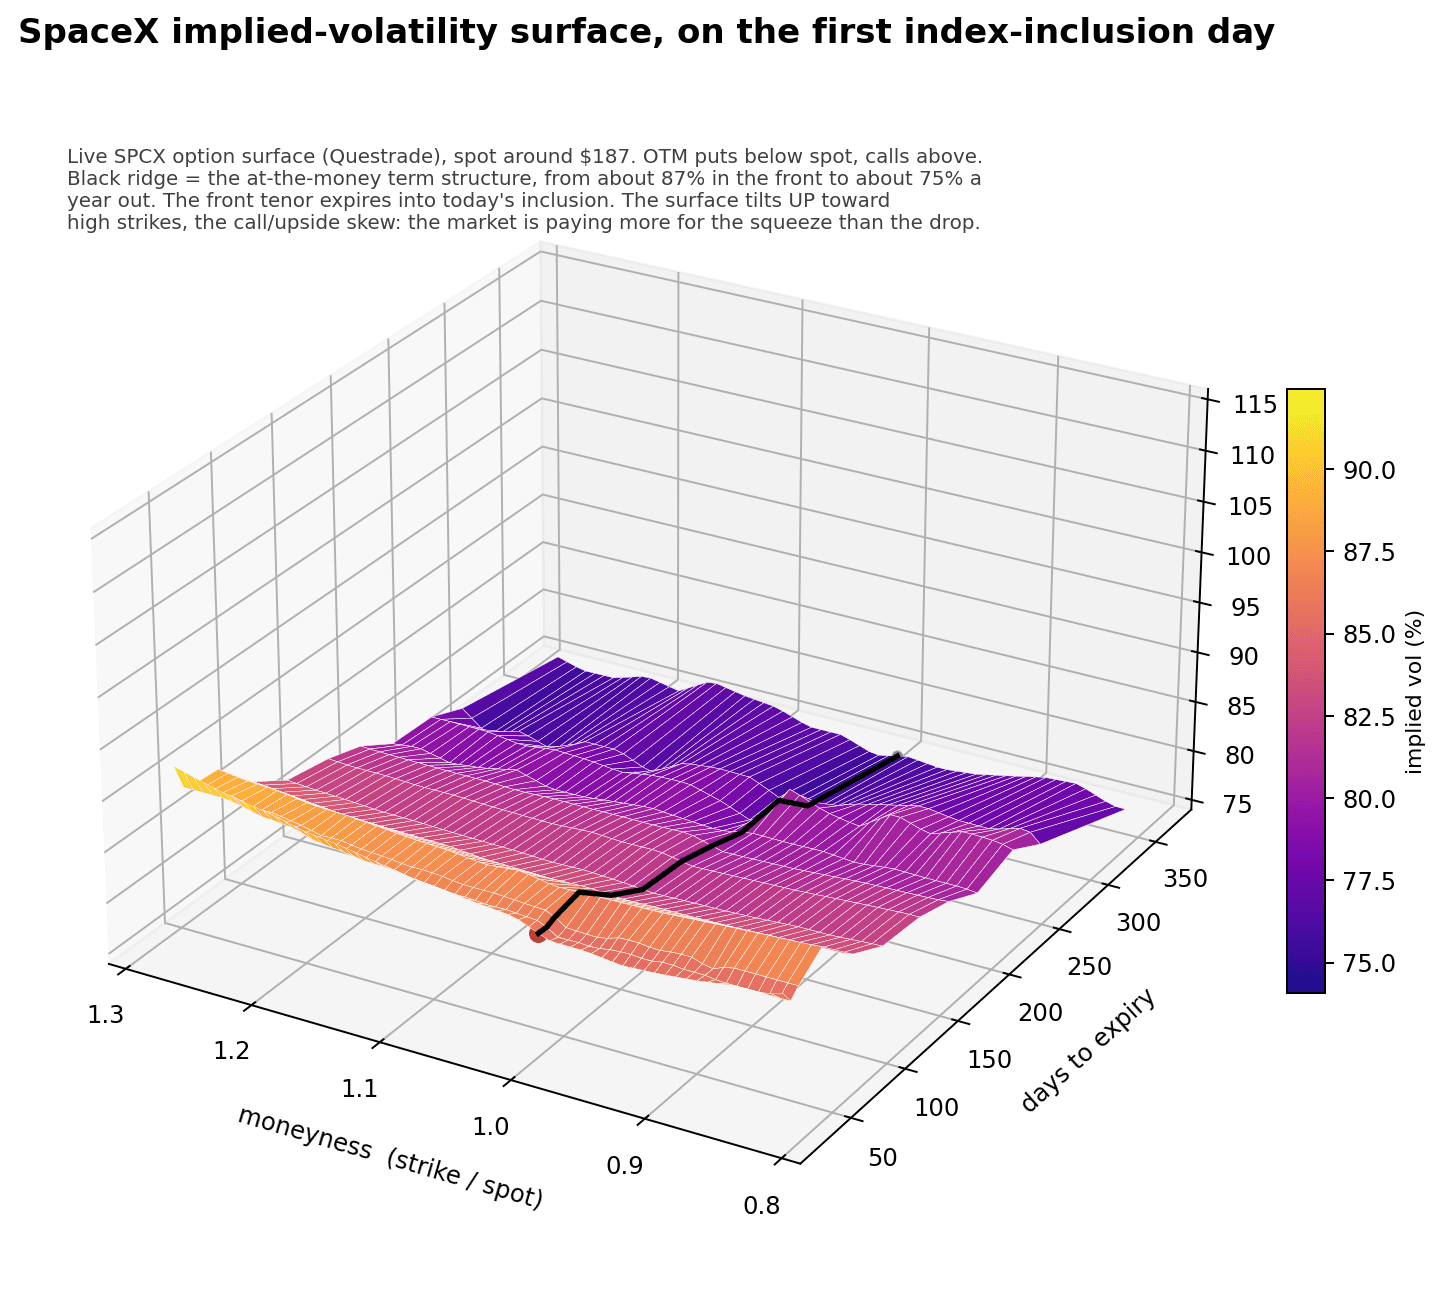
Stocks that retail investors crowd into on Reddit become more volatile the following week. Measured from 86.7 million comments, that signal is only about half absorbed by option prices. Short-dated implied volatility rises with attention but falls back over the next week, while the stock stays volatile.
Half the Signal: Retail Attention and the Price of Volatility

NextRetail investors as sellers of volatility, not only buyers, in progress

Working Papers

Featured Research

All papers
Working Paper2026

Indexing and the Elasticity of Stock Demand

with Carter Davis

Previously circulated as From Active to Passive: The Consequences for Demand Elasticity

IFMB 2025 Best Paper AwardFour Corners/FMRC 2025 Invited Paper (one of five)

Passive investing makes stock demand less responsive to price. How much depends on who else holds the shares. Measuring indexing from portfolio holdings, including benchmark overlap inside active funds, we find that the most indexed stocks have demand about half as elastic as the least indexed. Index fund families' larger ownership explains only a quarter of this gap. Most comes from other owners whose low price sensitivity extends across their portfolios. At the Russell cutoff, added index ownership lowers elasticity while other owners' price sensitivity changes little. Index demand raises prices far more than it raises fundamental value.

JEL:G11, G12, G14, G23Keywords:passive investing, demand elasticity, index inclusion, Active Share, closet indexing, demand system, asset pricing

Presented at:NFA 2026 · MFA 2026 · Four Corners/FMRC 2025 · IFMB 2025 · HEC Montréal 2025 · FMA 2024

Working Paper2026

The Price of Passive Ownership

Previously circulated as The Passive Paradox

FMA 2025 Best Paper Award (Asset Pricing) — Semi-Finalist

During the rise of passive investing, heavily indexed stocks outperformed lightly indexed stocks, yet are priced to earn less. As indexed capital moved in, prices rose faster than earnings forecasts, rewarding existing shareholders and lowering expected returns for subsequent buyers. The gains remained five years later. Passive investing repeatedly grew faster than forecast, and heavily indexed stocks earned more when it did. Four empirical designs put the price of a percentage point of indexed ownership at about 1.4 percent of stock value. Lower expected returns are the price of passive ownership.

JEL:G11, G12, G23Keywords:asset pricing, institutional investors, index effect, passive investing, mutual funds, ETFs

Presented at:FMA 2025 · ESG UQAM 2025 · FMA 2023 Doctoral Student Consortium

Working Paper2026

Who Gets Credit When Carbon Scores Fall?

with Evan Jo

A fund can look greener without its manager shifting the portfolio toward greener firms. Since 2019, U.S. fund carbon intensity has fallen by about a third, yet managers' trading explains less than a tenth. Carbon intensity divides emissions by sales; rising sales drove most of the decline and output prices half. Forty-four percent of funds credited with a decline did not trade it down. Those prices carry most of a leading estimate of brown firms' response to cheaper capital, and sales, not carbon, carry the carbon premium. Carbon scores measure portfolio exposure; attribution reveals who deserves credit for changing it.

JEL:G11, G14, G23, Q54Keywords:delegated portfolio management, performance attribution, ESG ratings, carbon footprints, sustainability ratings, institutional investors

Presented at:GRASFI-Asia 2027 (scheduled)

Working Paper2026

Half the Signal: Retail Attention and the Price of Volatility

Retail investors reveal in public which stocks they are crowding into, and those stocks become more volatile the following week. Using 86.7 million Reddit comments, I show that the full implied volatility surface absorbs only about half of this public signal. Option prices do react, but not for long. Short-maturity implied volatility is higher when attention is high and falls over the next week while stock volatility remains elevated. Delta-hedged option buyers earn lower subsequent gains. The unabsorbed half improves volatility forecasts out of sample. Controlling for implied volatility does not control for what retail attention predicts.

JEL:G12, G13, G14, G40Keywords:retail investor attention, Reddit, social media, implied volatility surface, volatility forecasting, market efficiency

Presented at:International Behavioural Finance Conference 2026, Chicago Booth

Working Paper2026

Predictable Demand and the Price of New Shares

Previously circulated as Passive Investing and the Supply of New Shares

Index funds must buy part of every new issue by firms they already hold, in amounts and on dates index rules set before the deal is priced. These purchases grew from about 2 percent of dollars raised in seasoned offerings in 2002 to nearly 16 percent in 2023. Firms selling into more of this scheduled demand sell at higher prices once the deal is public, and the issue-size discount nearly disappears among the most passively owned issuers, far beyond what removing the purchased shares from the market would give. Sales of existing shares show no such pattern. At Russell share updates turnover rises on the close, and in lower-priced issuers the price rises into it. A growing share of new equity sells into demand known in advance.

Keywords:index recognition, seasoned equity offerings, passive investing, liquidity provision
IXI: Indexing Inclusion Ratio

A new measure of realized indexed ownership

IXI measures each stock's indexed ownership monthly from portfolio holdings: the shares held by index funds plus the benchmark overlap inside nominally active funds. Unlike flow-based or classification-based proxies, IXI isolates the actual indexed footprint in each stock, enabling cleaner identification of how indexing affects demand, prices, and expected returns across the cross-section.

Subscribe

Get new articles by email

A short email when there is a new piece. No newsletter blast, no tracking, no shared lists. Unsubscribe any time.

No tracking. Unsubscribe any time.

About

I am an Assistant Professor of Finance at ESG UQAM (École des sciences de la gestion, Université du Québec à Montréal). I received my PhD in Finance from McGill University in 2024 and hold an MSc in Finance and Economics from the London School of Economics.

My research centers on the shift from active to passive investing and its consequences for equity markets. I construct the Indexing Inclusion Ratio (IXI), which measures each stock's indexed ownership from portfolio holdings, including benchmark overlap inside active funds. With Carter Davis, I use it to show that the most indexed stocks have demand about half as elastic as the least indexed. In related work, I find that heavily indexed stocks outperformed during the rise of passive investing yet are priced to earn less, and that firms selling new shares into more of index funds' scheduled demand sell them at higher prices. A project with Laurent Barras and David Schumacher studies how active fund managers respond to the growing dominance of passive capital.

A second line of work asks what falling carbon scores in delegated portfolios actually measure. With Evan Jo, I show that U.S. fund carbon intensity has fallen by about a third since 2019, yet managers' trading explains less than a tenth of the decline; rising sales drove most of it. A third line of work studies retail investors in option markets. Measuring retail attention from 86.7 million Reddit comments, I find that the implied volatility surface absorbs only about half of what that attention predicts about a stock's volatility the following week.